Seven-year programme includes $700 million in R&D, Hyundai and Kia capacity expansion, supplier development and new mobility businesses, as the group widens its presence beyond passenger cars.
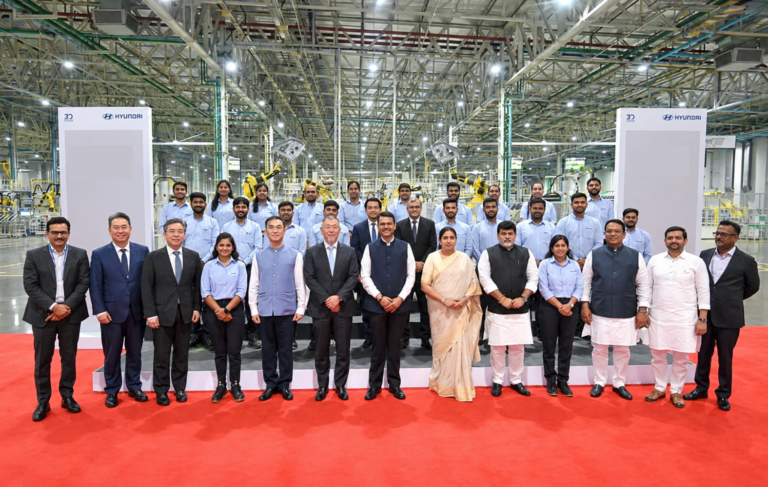
Hyundai Motor Group has announced a $15.5 billion investment programme for India between 2026 and 2032, covering research and development, manufacturing expansion, local sourcing and new mobility businesses.
The group plans to expand its Indian engineering operations and increase manufacturing capacity at Hyundai Motor India and Kia India. It will also explore businesses in automotive financing, EV charging and vehicle recycling.
A dedicated investment entity will be established in India to oversee the programme and identify local suppliers, technology partners and investment opportunities.
The initiative was discussed during a meeting between Prime Minister Narendra Modi and Hyundai Motor Group Executive Chair Euisun Chung in New Delhi on October 13, according to the group.
“India remains one of Hyundai Motor Group’s most important and strategic markets globally. The past 30 years have been defined by our commitment to India. This investment reaffirms our commitment to India for the next 30 years and beyond,” Chung said.
“Through this investment, we will create more employment opportunities and work together with our partners and stakeholders to support India’s continued industrial development.”
The announcement follows Autocar Professional’s reports on Hyundai’s planned R&D expansion in Telangana, its search for a third manufacturing location and Kia’s evaluation of additional capacity at Anantapur.
$700 Million for Indian R&D
Hyundai Motor Group plans to invest approximately $700 million in its Indian R&D centre, including a vehicle testing track. The spending will expand engineering infrastructure and support the development of automotive technologies and local talent.
Autocar Professional reported in May 2025 on Telangana’s approval of a proposed Rs 8,528 crore Hyundai R&D centre, citing a New Indian Express report.
That proposal covered a Hyundai Global Innovation Research and Development Centre on 675 acres at Zaheerabad, with a test track, pilot line and prototyping facilities. The report also noted that Hyundai’s existing Hyderabad engineering centre was being expanded to support global compact passenger vehicle development.
The latest release does not explain how the $700 million allocation relates to the earlier Telangana proposal.
he group plans to expand manufacturing across Hyundai Motor India and Kia India to meet demand, increase localisation and support exports.
Its combined annual production capacity in India currently exceeds 1.4 million vehicles. This includes Hyundai’s Chennai facilities with a capacity of 824,000 units, its Pune facility with 170,000 units, and Kia’s Anantapur plant with 431,000 units.
Capacity at Pune is scheduled to increase in phases. Hyundai is also assessing a third manufacturing location to meet its longer-term requirements.
Autocar Professional reported on September 29 that Chhatrapati Sambhaji Nagar in Maharashtra and Sanand in Gujarat were among the locations under consideration.
According to people familiar with the plans, the proposed facility could eventually add around 500,000 units of annual capacity, with investment potentially exceeding $2 billion over time. The plant could come up around 2030, with capacity added in phases over five to seven years.
The discussions were at an early stage, with the location, investment schedule and product allocation yet to be finalised. Hyundai had declined to comment on market speculation.
The October 13 announcement does not identify a third plant location or disclose the additional manufacturing capacity planned under the programme.
Kia Evaluates Additional Capacity
Kia is also studying expansion at Anantapur as it prepares to introduce more products and powertrain options.
Autocar Professional reported on August 15 that Kia was evaluating a new production line with annual capacity of around 2 lakh units.
People familiar with the development said the supplier ecosystem had been sounded out as part of the assessment, although a final investment decision had yet to be taken.
Kia did not specifically confirm the proposed line, but said it would scale operations in line with market growth and customer demand. The company is targeting domestic sales of around 4.1 lakh units by 2030 and preparing a wider range of hybrid and electric products.
The group has not disclosed the investment split between Hyundai and Kia or how individual capacity projects would fit into the $15.5 billion commitment.
Moving Beyond Passenger Cars
Hyundai has explored opportunities in buses in the past and is now developing electric three-wheelers with TVS Motor Company, widening its interests in India beyond passenger cars.
Autocar Professional reported that the Hyundai–TVS electric three-wheeler is targeting a late-2027 to early-2028 launch. The companies have signed a joint development agreement to commercialise electric three-wheelers for India and additional markets.
The TVS partnership takes Hyundai into India’s electric three-wheeler market. Under the broader investment programme, the group also plans to support promising startups and expand into mobility services linked to its vehicle business.
Specialised automotive financing, EV charging infrastructure and end-of-life vehicle recycling are among the areas it will explore.
Building Local Supplier Capabilities
Hyundai Motor Group plans to invest in regional partners to increase parts localisation, develop suppliers and strengthen its Indian supply chain.
The group already operates component and service businesses in India through affiliates including Hyundai Mobis, Hyundai Transys, Hyundai Capital, Hyundai Wia and Hyundai Glovis.
It employs more than 24,000 people across the country. It expects the investment to create jobs in manufacturing, R&D, engineering and supply chains, both within its operations and through suppliers and new mobility ventures.
The programme gives India a larger role in the group’s engineering and production plans, while opening opportunities beyond its established passenger vehicle business. The proposed investments in suppliers, charging, financing and recycling would also expand its presence across the wider automotive market.
Total car sales reached 183,704 units during the period, the PAMA said.
Total car sales reached 183,704 units during the period, the association said.
In May 2026 alone, vehicle sales rose 19% year-on-year to 17,660 units. However, sales declined 20% month-on-month, which analysts attributed to Eid-related holidays.
Motorcycle and three-wheeler sales reached 172,433 units in May, reflecting a 13% year-on-year decline and a 10% monthly drop. Despite this, total sales for the 11-month period stood at 1.8 million units, marking a 30% annual increase.
Among major manufacturers, Suzuki reported a 75% rise in monthly sales to 8,856 units. Honda Atlas posted an 11% increase with 2,230 units sold, while Hyundai Nishat saw a 31% decline, with sales dropping to 902 units.
Industry officials said the overall growth reflects gradual economic recovery and improved consumer demand in the auto sector.
Earlier, The International Monetary Fund (IMF) has pushed back against a proposed reduction in sales tax on imported electric vehicles, demanding the rate be set at 25 percent rather than the 1 percent floated by Pakistani authorities, sources said Wednesday.
The fund classified imported EVs as luxury goods despite their environmental credentials, opposing any tax concession on the vehicles, sources said.
The development comes as Prime Minister Shehbaz Sharif has directed officials to protect jobs in domestic industries ahead of the upcoming federal budget.
The government is considering a package of relief measures for the local auto manufacturing sector in the next fiscal year. Raw material imports for the domestic auto industry could be taxed at just 1 percent, while import duties on parts used to manufacture locally assembled vehicles may be halved from 10 percent to 5 percent.
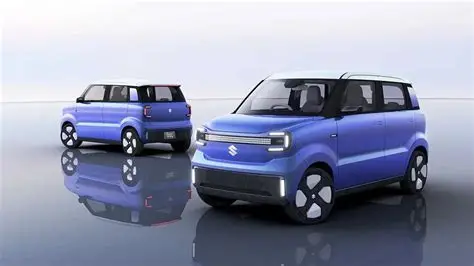
Suzuki Motor Corp will launch an ultracompact electric vehicle model in November in Japan in the hope of enticing customers with affordable prices in intensifying competition with BYD Co. and other rivals in the segment.
Set to go on sale on Nov 16, the e SKY offers a cruising range of around 310 kilometers on a single charge. After a government subsidy of 568,000 yen, the prices of the small EV start at 1.55 million yen.
Suzuki has set a monthly sales target of 1,000 vehicles.
“This is an answer that only Suzuki, which has continued to build and refine minicars, could have arrived at,” President Toshihiro Suzuki said at an event for the new model in Tokyo.
Suzuki, one of Japan’s two largest minicar makers, is making its long-awaited entry into the EV segment as competition intensifies.
In July, China’s BYD became the first overseas carmaker to enter Japan’s mini EV market, launching the Racco with a starting price of around 2 million yen after government subsidies. About 650 Raccos had been sold by the end of September, according to the Japan Light Motor Vehicle and Motorcycle Association.
Among other EV models, Nissan Motor Co’s Sakura is available from about 1.87 million yen and Honda Motor Co’s N-ONE e: from around 2.12 million yen, both helped by government subsidies.
Suzuki, a latecomer to the segment, saw no need to be the first to enter the market, the president said.
“While learning from other automakers, we discussed what a mini EV should be and took time to develop it carefully,” he said.
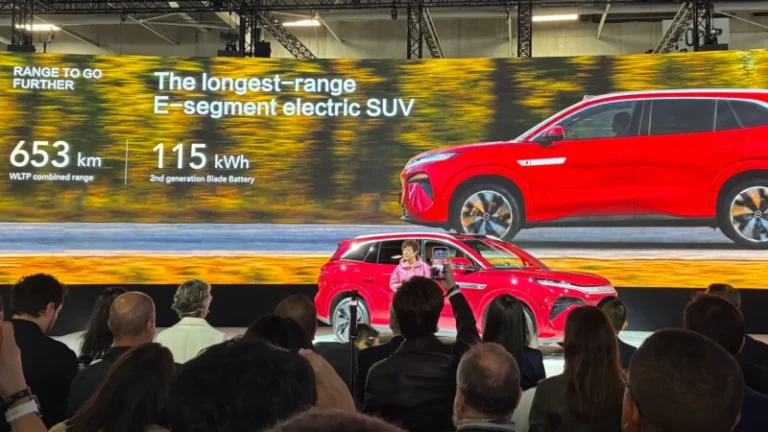
The BYD Atto 8, known domestically as the BYD Tang L, became the brand’s first model with flash charging in Europe. It made an official debut at the Paris Auto Show 2026 with seven seats, a peak power of 764 hp, and a 136-liter frunk with a double-tap opening function. BYD executive vice president Stella Li presented the car.
The BYD Atto 8 boasts the second-generation LFP Blade Battery from BYD. It offers a capacity of 115 kWh, suitable for 653 km of range under WLTP conditions. The biggest highlight of this pack is the flash charging function. It allows charging from 10% to 97% in nine minutes. The charging time from 10% to 70% is five minutes. The charging time increases by 3 minutes at minus 30 degrees Celsius. BYD plans to establish 6,000 flash chargers in foreign countries by the end of 2027.
According to BYD officials, the Atto 8 is the most powerful 7-seat SUV in Europe. It offers a combined peak power output of 570 kW (764 hp, 775 ps). As a result, this model accelerates to 100 km/h in 4.6 seconds. The top speed reaches 240 km/h. The Atto 8 might be the most powerful seven-seater, but not the fastest. For example, the Audi SQ7 speeds up to 100 km/h in 4.1 seconds.
The BYD Atto 8 is a large crossover with dimensions of 5040/1996/1760 mm and a wheelbase of 2,950 mm. Despite being available with five seats only domestically, this EV will offer three rows of seats in Europe with a 2+3+2 layout. The BYD Atto 8 has a 136-liter frunk that could be opened by double-tap. Another highlight is a projection-activated power tailgate.
The BYD Atto 8 will start sales in Europe in Q1 2027. The price tag of this car has yet to be revealed. For clarity, the brand’s current seven-seater for Europe, the Tang EV, costs 75,000 EUR (83,885 USD) in Germany. However, according to the brand’s official website, the Tang’s price was reduced to 47,990 EUR (53,675 USD).
The BYD Tang L EV (Atto 8 EV) costs 222,800 – 272,800 yuan (33,290 – 40,765 USD) domestically. According to China EV DataTracker, BYD handed over just 4,426 units of this model to owners in China from January to August 2026, down 87.5% Year-Over-Year.
Japanese conglomerate tells PM Tarique Rahman it aims to begin work on a hybrid electric vehicle plant in an economic zone in 2027
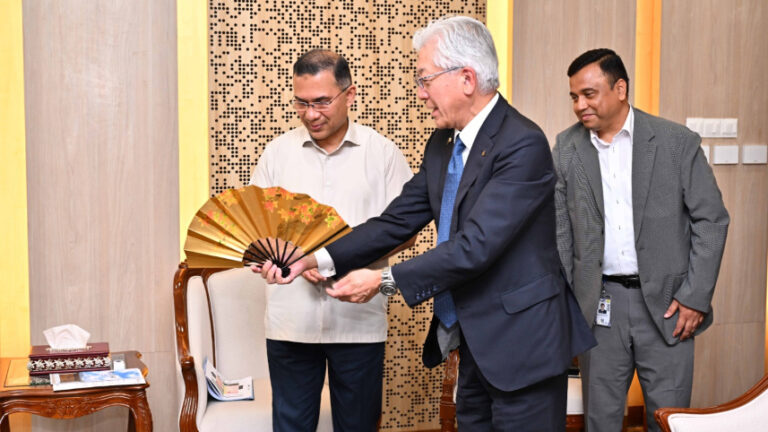
Toyota Tsusho Corporation is exploring plans to manufacture vehicles in Bangladesh, with a high-level delegation from the Japanese company briefing Prime Minister Tarique Rahman on its proposed investment on Tuesday.
The delegation, led by Toyota Tsusho Vice Chairman Ichiro Kashitani, met the prime minister at his office in the Secretariat and informed him of the company’s plan to establish a Toyota vehicle manufacturing plant in Bangladesh, said PM’s Deputy Press Secretary Shahadat Hossain Shadhin.
loyment generation, industrialisation expansion, technology transfer, and the development of skilled human resources in the country.
The two sides also discussed expanding Toyota’s operations in Bangladesh, potential investment opportunities, and the company’s long-term business plans.
Tarique welcomed Toyota Tsusho’s interest in expanding its investment and operations in Bangladesh.
He said the government is working to ensure a stable, competitive, and investment-friendly environment for both domestic and foreign investors.
The prime minister said the government is committed to providing necessary policy support, infrastructure facilities, and other opportunities to foreign investors.
He also highlighted the potential of waste-to-energy and renewable energy in Bangladesh, saying the government will provide necessary support if Toyota Tsusho is interested in investing in these sectors.
The Toyota delegation said its plan to expand Toyota Bangladesh’s distribution network to all divisional cities is already underway.
The expansion is aimed at making Toyota’s services and operations more accessible across the country.
The company also informed the prime minister that Toyota Bangladesh will begin work in 2027 to establish a Hybrid Electric Vehicle (HEV) manufacturing industry in an economic zone under the development vision of “With Bangladesh, for Bangladesh”, with full-scale production targeted for 2029.
Toyota also expressed interest in contributing to human resources development in Bangladesh, particularly by creating technical and vocational training opportunities for young people, enhancing their skills and developing a workforce suited to future industries.
Commerce Minister Khandakar Abdul Muktadir, Prime Minister’s Adviser on Finance and Planning Rashed Al Mahmud Titumir, State Minister for Foreign Affairs Humaiun Kobir, Prime Minister’s Adviser on Science and Technology Rehan Asif Asad, and Prime Minister’s Special Assistant for Overseas Employment Affairs in the Asia-Pacific Region Md Shakirul Islam Khan, among others, attended the meeting.
Toyota Tsusho Mobility Division CEO Shigeru Harada, President of Toyota Bangladesh Ltd Premmit Singh and other senior officials of the company were also present.
Toyota Tsusho is the trading arm of the Toyota Group, which includes Toyota Motor and auto parts maker DENSO.
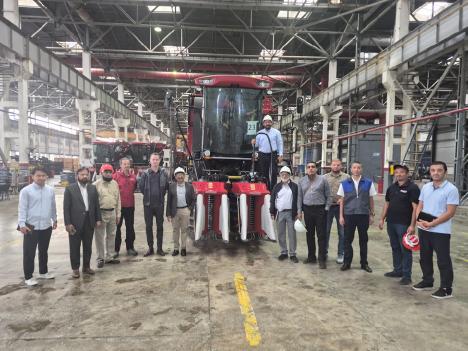
A delegation of Pakistani cotton experts witnessed a demonstration of a new 2-row cotton picker by Case New Holland (CNH) in Tashkent, Uzbekistan, generating considerable interest in the potential of mechanized cotton harvesting for Pakistan.
Cotton production in Pakistan is facing increasing challenges, including pest attacks associated with excessive humidity, labor shortages, climate change, adulterated pesticides, and low-vigor seed. Mechanization of cotton harvesting is therefore being considered as one of the potential solutions to address some of these challenges.
The CNH cotton picker demonstrated in Tashkent is a self-propelled 2-row machine equipped with a dual-side picking system. It has an average productivity of 1.33 tons per hour, with a reported picking efficiency of 90–95 percent. The machine’s row spacing is compatible with Pakistan’s prevailing cotton sowing pattern of 76 cm, while the spacing can be adjusted to 76, 81, 90 and 100 cm.
The Pakistani delegation also participated in a classroom discussion following the field demonstration, where technical and agronomic aspects of mechanized cotton harvesting were discussed.
The delegation comprised Dr. Zahid Mahmood, Former Cotton Commissioner; Mr. Muhammad Jameel, Director, Cotton Research Institute (CRI), Multan; Mr. Yasir Jan Khan, a leading cotton grower; Dr. Alamgir Khan, Mechanization Expert; and Engr. Adnan Iqbal from Farm3vo Technologies (Pvt.) Ltd (A company of AlKaram group) CNH distributor in Pakistan.
Addressing the participants, Dr. Zahid said that Pakistan has the capability to develop and provide a cotton variety suitable for mechanical harvesting, particularly a variety that can be harvested effectively in a single picking.
Representatives of Case New Holland, including Mr. Wojciech Purczynski; Mr. Sala Massimiliano; Engr. Mansoor Rizvi, CNH Country Manager, Pakistan; BURKHANOV Oybek and Mr. Hall Brian, briefed the Pakistani delegation on the machine’s technical features and its potential benefits for Pakistan’s cotton crop.
The visit provided an opportunity for Pakistani cotton experts to assess the suitability of mechanized cotton harvesting under local crop conditions and to exchange views with CNH specialists on the prospects and challenges of introducing cotton-picking technology in Pakistan.
Chery Master Offers PKR 1.29 Million Upfront Savings on Tiggo 8 Super Hybrid AWD
Limited Stock Price Lock Offer with a complimentary 7 kW Home Charger worth PKR 100,000
KARACHI, October 9 2026: Chery Master Pakistan is giving customers more than just a better way to drive. The Chery Tiggo 8 Super Hybrid is Pakistan’s best-value 7-seater plug-in hybrid SUV, combining AWD capability, six driving modes, premium comfort, advanced technology and strong performance. With the applicable sales tax on PHEVs nearly doubling, the Chery Tiggo 8 Super Hybrid is now available at PKR 10,999,000 against its original price of PKR 12,289,000, giving customers an upfront saving of PKR 1.29 million under the Limited Stock Price Lock Offer. The offer also includes a complimentary 7 kW home charger worth PKR 100,000, adding further value from day one.
The biggest saving comes every time you drive.
Fuel has become one of the biggest ongoing costs of owning a car in Pakistan. With petrol prices approaching PKR 400 per litre, a comparable petrol car averaging around 8 km/l can consume approximately PKR 100,000 in fuel every month for a 2,000-kilometre monthly drive, translating into nearly PKR 1 million in fuel costs over 20,000 km.
This is Fuel Anxiety: the cost and uncertainty that comes with every kilometre driven.
The Chery Tiggo 8 Super Hybrid offers a different way forward. Powered by Chery Super Hybrid (CSH), its plug-in hybrid system combines electric driving for everyday mobility with petrol flexibility for longer journeys, allowing customers to reduce fuel dependency without giving up the SUV they want.
With up to 90 kilometres of pure electric range and a combined range of around 1,200 kilometres, the Chery Tiggo 8 Super Hybrid operates as an electric-priority vehicle, enabling most daily driving without fuel while retaining the flexibility needed for longer journeys. And for customers with solar at home, the energy already being generated on their rooftop can power their everyday electric driving, turning their solar investment into mobility.
As Pakistan’s only 7-seater plug-in hybrid D-SUV, it brings three full rows of seating into the PHEV category, giving customers the space to bring the whole family along in one car, without needing an additional vehicle and another fuel bill.
Its performance matches its capability, with 496 horsepower, 735 Nm of torque and 0–100 km/h in just 6.8 seconds, making it one of the most powerful SUVs in the D segment.
Inside, the Chery Tiggo 8 Super Hybrid is one of the most feature-rich SUVs in its class, with a Queen Co-Pilot zero-gravity massage seat, heated and ventilated front seats, 15.6-inch HD infotainment display, digital instrument cluster, 12-speaker Sony premium audio system and immersive ambient lighting.
Chery ranks No. 1 among Chinese brands in J.D. Power in Quality. The Tiggo 8 Super Hybrid also carries a 5-star global safety rating, with 10 airbags, 23+ active safety features and Level 2 ADAS, alongside Euro 6B compliance.
You don’t have to give up the SUV you want to escape the fuel bill. You can change what powers it.
Introduced through Master Auto Engineering, part of Master Group, in partnership with Chery Automobile, China’s No. 1 automotive exporter for 23 consecutive years.
Backed by Master Group’s 60+ years of legacy and 40+ years in automotive, Chery Master Pakistan is building the next chapter of New Energy mobility in Pakistan. With 14 fully operational 3S dealerships across Pakistan and plans to expand to 20 by 2027, Chery Master is rapidly expanding nationwide access and after-sales support for its growing customer base.
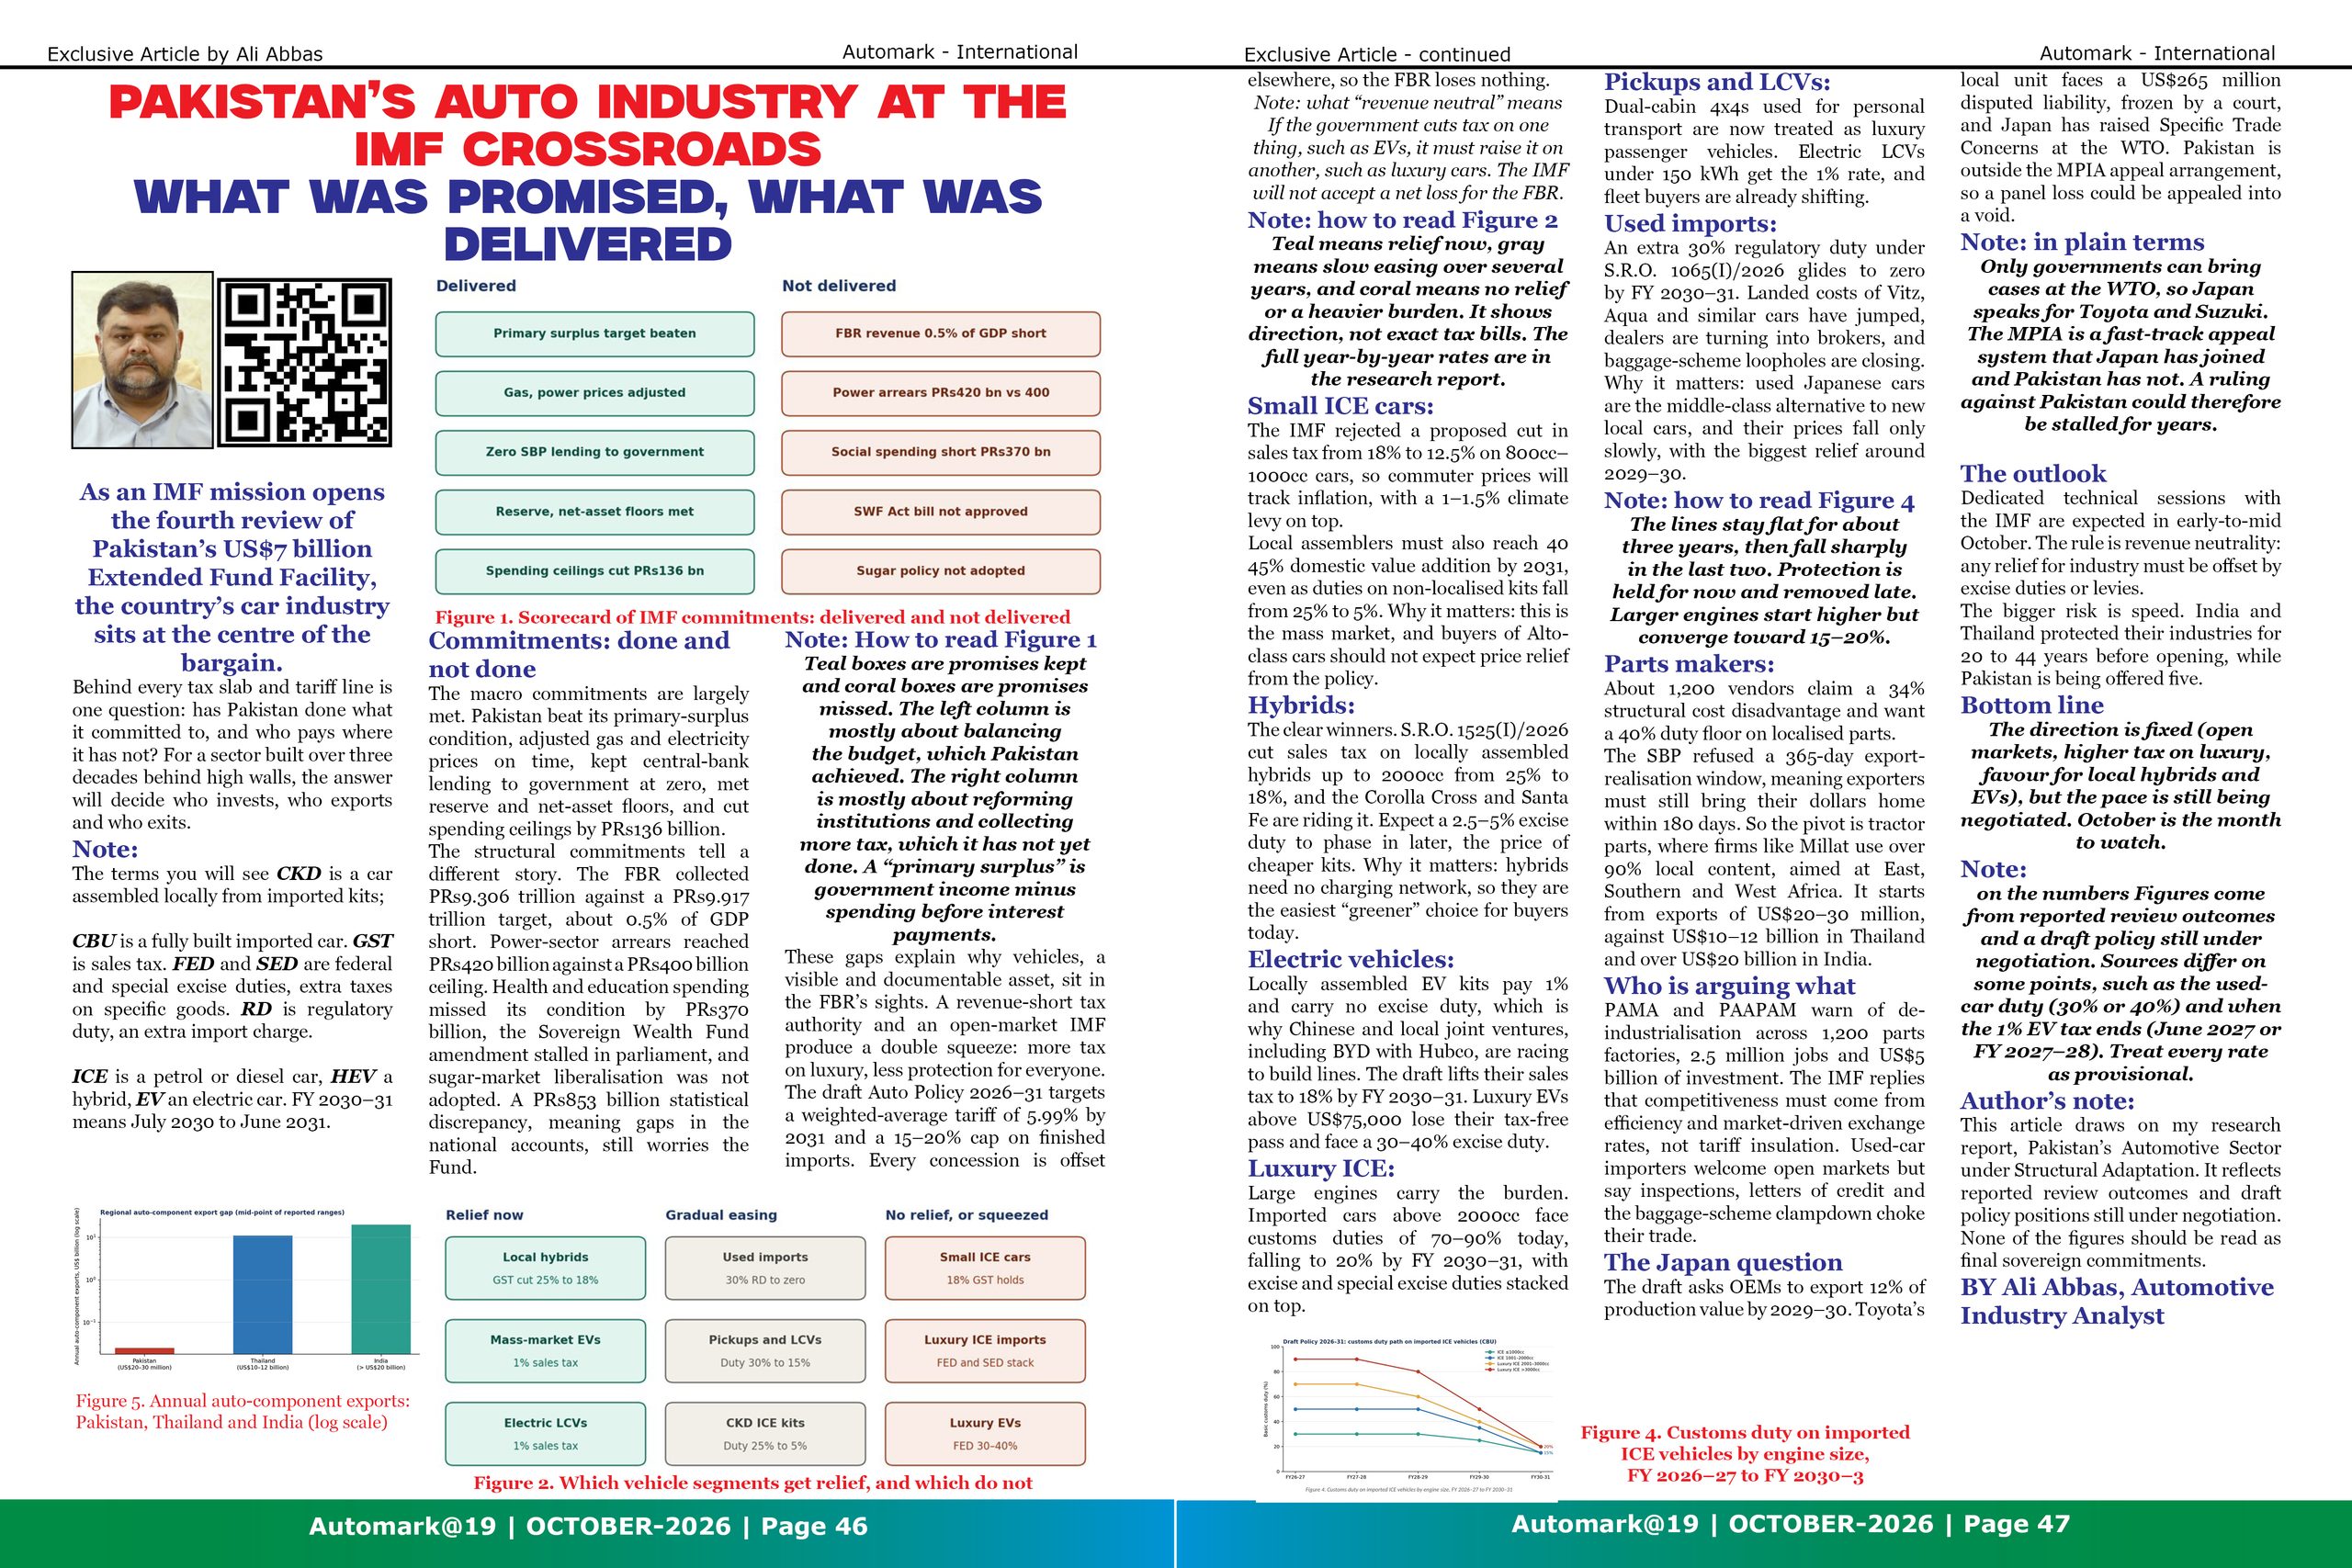
As an IMF mission opens the fourth review of Pakistan’s US$7 billion Extended Fund Facility, the country’s car industry sits at the centre of the bargain. Behind every tax slab and tariff line is one question: has Pakistan done what it committed to, and who pays where it has not? For a sector built over three decades behind high walls, the answer will decide who invests, who exports and who exits.
Note: the terms you will see CKD is a car assembled locally from imported kits; CBU is a fully built imported car. GST is sales tax. FED and SED are federal and special excise duties, extra taxes on specific goods. RD is regulatory duty, an extra import charge. ICE is a petrol or diesel car, HEV a hybrid, EV an electric car. FY 2030–31 means July 2030 to June 2031.
Commitments: done and not done
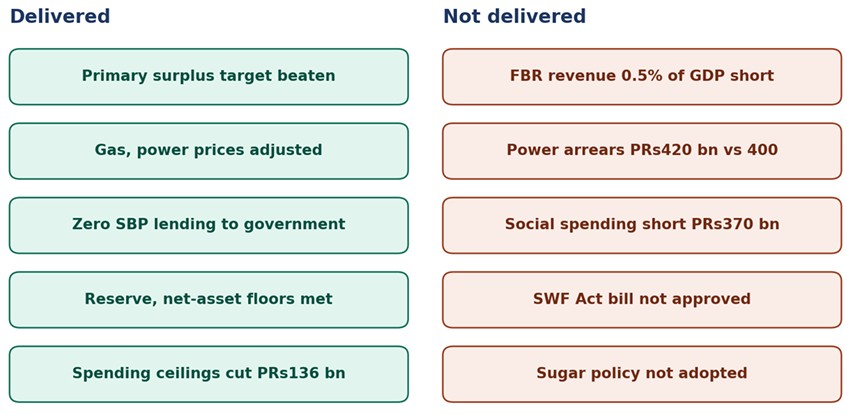
The macro commitments are largely met. Pakistan beat its primary-surplus condition, adjusted gas and electricity prices on time, kept central-bank lending to government at zero, met reserve and net-asset floors, and cut spending ceilings by PRs136 billion.
The structural commitments tell a different story. The FBR collected PRs9.306 trillion against a PRs9.917 trillion target, about 0.5% of GDP short. Power-sector arrears reached PRs420 billion against a PRs400 billion ceiling. Health and education spending missed its condition by PRs370 billion, the Sovereign Wealth Fund amendment stalled in parliament, and sugar-market liberalisation was not adopted. A PRs853 billion statistical discrepancy, meaning gaps in the national accounts, still worries the Fund
Note: how to read Figure 1
Teal boxes are promises kept and coral boxes are promises missed. The left column is mostly about balancing the budget, which Pakistan achieved. The right column is mostly about reforming institutions and collecting more tax, which it has not yet done. A “primary surplus” is government income minus spending before interest payments.
These gaps explain why vehicles, a visible and documentable asset, sit in the FBR’s sights. A revenue-short tax authority and an open-market IMF produce a double squeeze: more tax on luxury, less protection for everyone. The draft Auto Policy 2026–31 targets a weighted-average tariff of 5.99% by 2031 and a 15–20% cap on finished imports. Every concession is offset elsewhere, so the FBR loses nothing.
Note: what “revenue neutral” means
If the government cuts tax on one thing, such as EVs, it must raise it on another, such as luxury cars. The IMF will not accept a net loss for the FBR
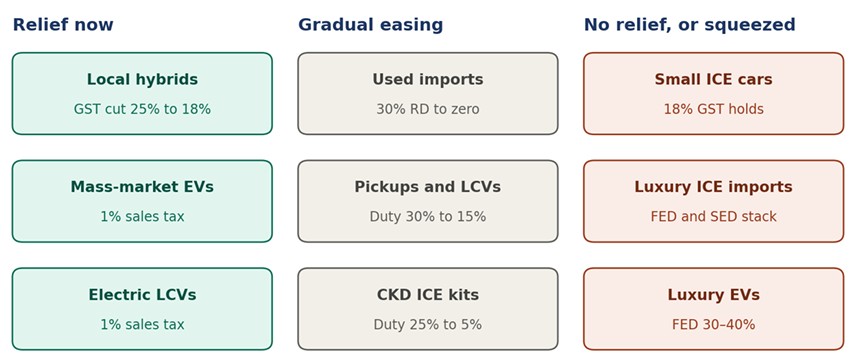
Note: how to read Figure 2
Teal means relief now, gray means slow easing over several years, and coral means no relief or a heavier burden. It shows direction, not exact tax bills. The full year-by-year rates are in the research report.
Small ICE cars. The IMF rejected a proposed cut in sales tax from 18% to 12.5% on 800cc–1000cc cars, so commuter prices will track inflation, with a 1–1.5% climate levy on top. Local assemblers must also reach 40 45% domestic value addition by 2031, even as duties on non-localised kits fall from 25% to 5%. Why it matters: this is the mass market, and buyers of Alto-class cars should not expect price relief from the policy.
Hybrids. The clear winners. S.R.O. 1525(I)/2026 cut sales tax on locally assembled hybrids up to 2000cc from 25% to 18%, and the Corolla Cross and Santa Fe are riding it. Expect a 2.5–5% excise duty to phase in later, the price of cheaper kits. Why it matters: hybrids need no charging network, so they are the easiest “greener” choice for buyers today.
Electric vehicles. Locally assembled EV kits pay 1% and carry no excise duty, which is why Chinese and local joint ventures, including BYD with Hubco, are racing to build lines. The draft lifts their sales tax to 18% by FY 2030–31. Luxury EVs above US$75,000 lose their tax-free pass and face a 30–40% excise duty.
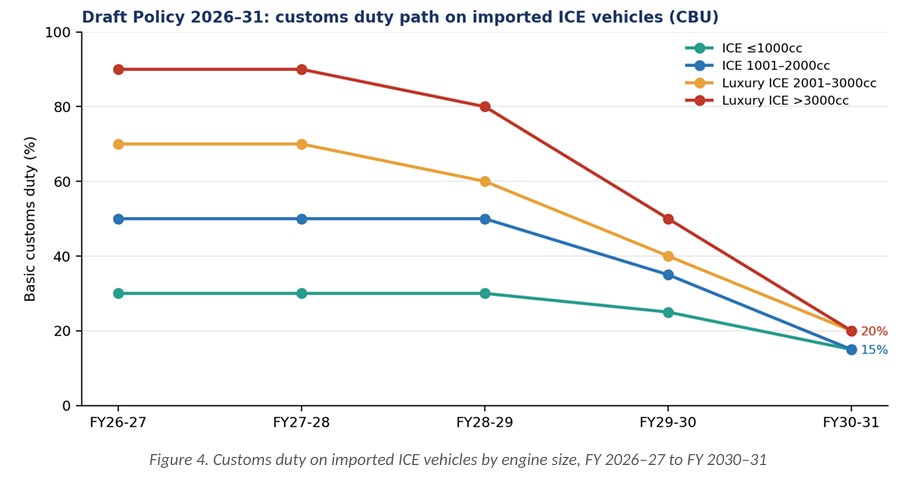
Luxury ICE. Large engines carry the burden. Imported cars above 2000cc face customs duties of 70–90% today, falling to 20% by FY 2030–31, with excise and special excise duties stacked on top.
Pickups and LCVs. Dual-cabin 4x4s used for personal transport are now treated as luxury passenger vehicles. Electric LCVs under 150 kWh get the 1% rate, and fleet buyers are already shifting.
Used imports. An extra 30% regulatory duty under S.R.O. 1065(I)/2026 glides to zero by FY 2030–31. Landed costs of Vitz, Aqua and similar cars have jumped, dealers are turning into brokers, and baggage-scheme loopholes are closing. Why it matters: used Japanese cars are the middle-class alternative to new local cars, and their prices fall only slowly, with the biggest relief around 2029–30.
Note: how to read Figure 4 The lines stay flat for about three years, then fall sharply in the last two. Protection is held for now and removed late. Larger engines start higher but converge toward 15–20%.
Parts makers. About 1,200 vendors claim a 34% structural cost disadvantage and want a 40% duty floor on localised parts. The SBP refused a 365-day export-realisation window, meaning exporters must still bring their dollars home within 180 days. So the pivot is tractor parts, where firms like Millat use over 90% local content, aimed at East, Southern and West Africa. It starts from exports of US$20–30 million, against US$10–12 billion in Thailand and over US$20 billion in India.
Who is arguing what PAMA and PAAPAM warn of de-industrialisation across 1,200 parts factories, 2.5 million jobs and US$5 billion of investment. The IMF replies that competitiveness must come from efficiency and market-driven exchange rates, not tariff insulation. Used-car importers welcome open markets but say inspections, letters of credit and the baggage-scheme clampdown choke their trade.
The Japan question The draft asks OEMs to export 12% of production value by 2029–30. Toyota’s local unit faces a US$265 million disputed liability, frozen by a court, and Japan has raised Specific Trade Concerns at the WTO. Pakistan is outside the MPIA appeal arrangement, so a panel loss could be appealed into a void.
Note: in plain terms only governments can bring cases at the WTO, so Japan speaks for Toyota and Suzuki. The MPIA is a fast-track appeal system that Japan has joined and Pakistan has not. A ruling against Pakistan could therefore be stalled for years.
The outlook
Dedicated technical sessions with the IMF are expected in early-to-mid October. The rule is revenue neutrality: any relief for industry must be offset by excise duties or levies.
The bigger risk is speed. India and Thailand protected their industries for 20 to 44 years before opening, while Pakistan is being offered five.
Bottom line The direction is fixed (open markets, higher tax on luxury, favour for local hybrids and EVs), but the pace is still being negotiated. October is the month to watch.
Note: on the numbers Figures come from reported review outcomes and a draft policy still under negotiation. Sources differ on some points, such as the used-car duty (30% or 40%) and when the 1% EV tax ends (June 2027 or FY 2027–28). Treat every rate as provisional.
Author’s note This article draws on my research report, Pakistan’s Automotive Sector under Structural Adaptation. It reflects reported review outcomes and draft policy positions still under negotiation. None of the figures should be read as final sovereign commitments. — Ali Abbas, Automotive Industry Analyst
This exclusive article has been published in Automark’s October-2026 printed and digital edition.
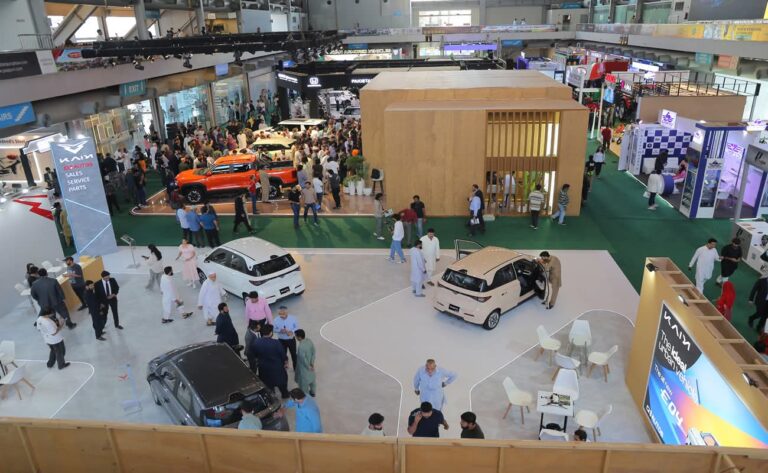
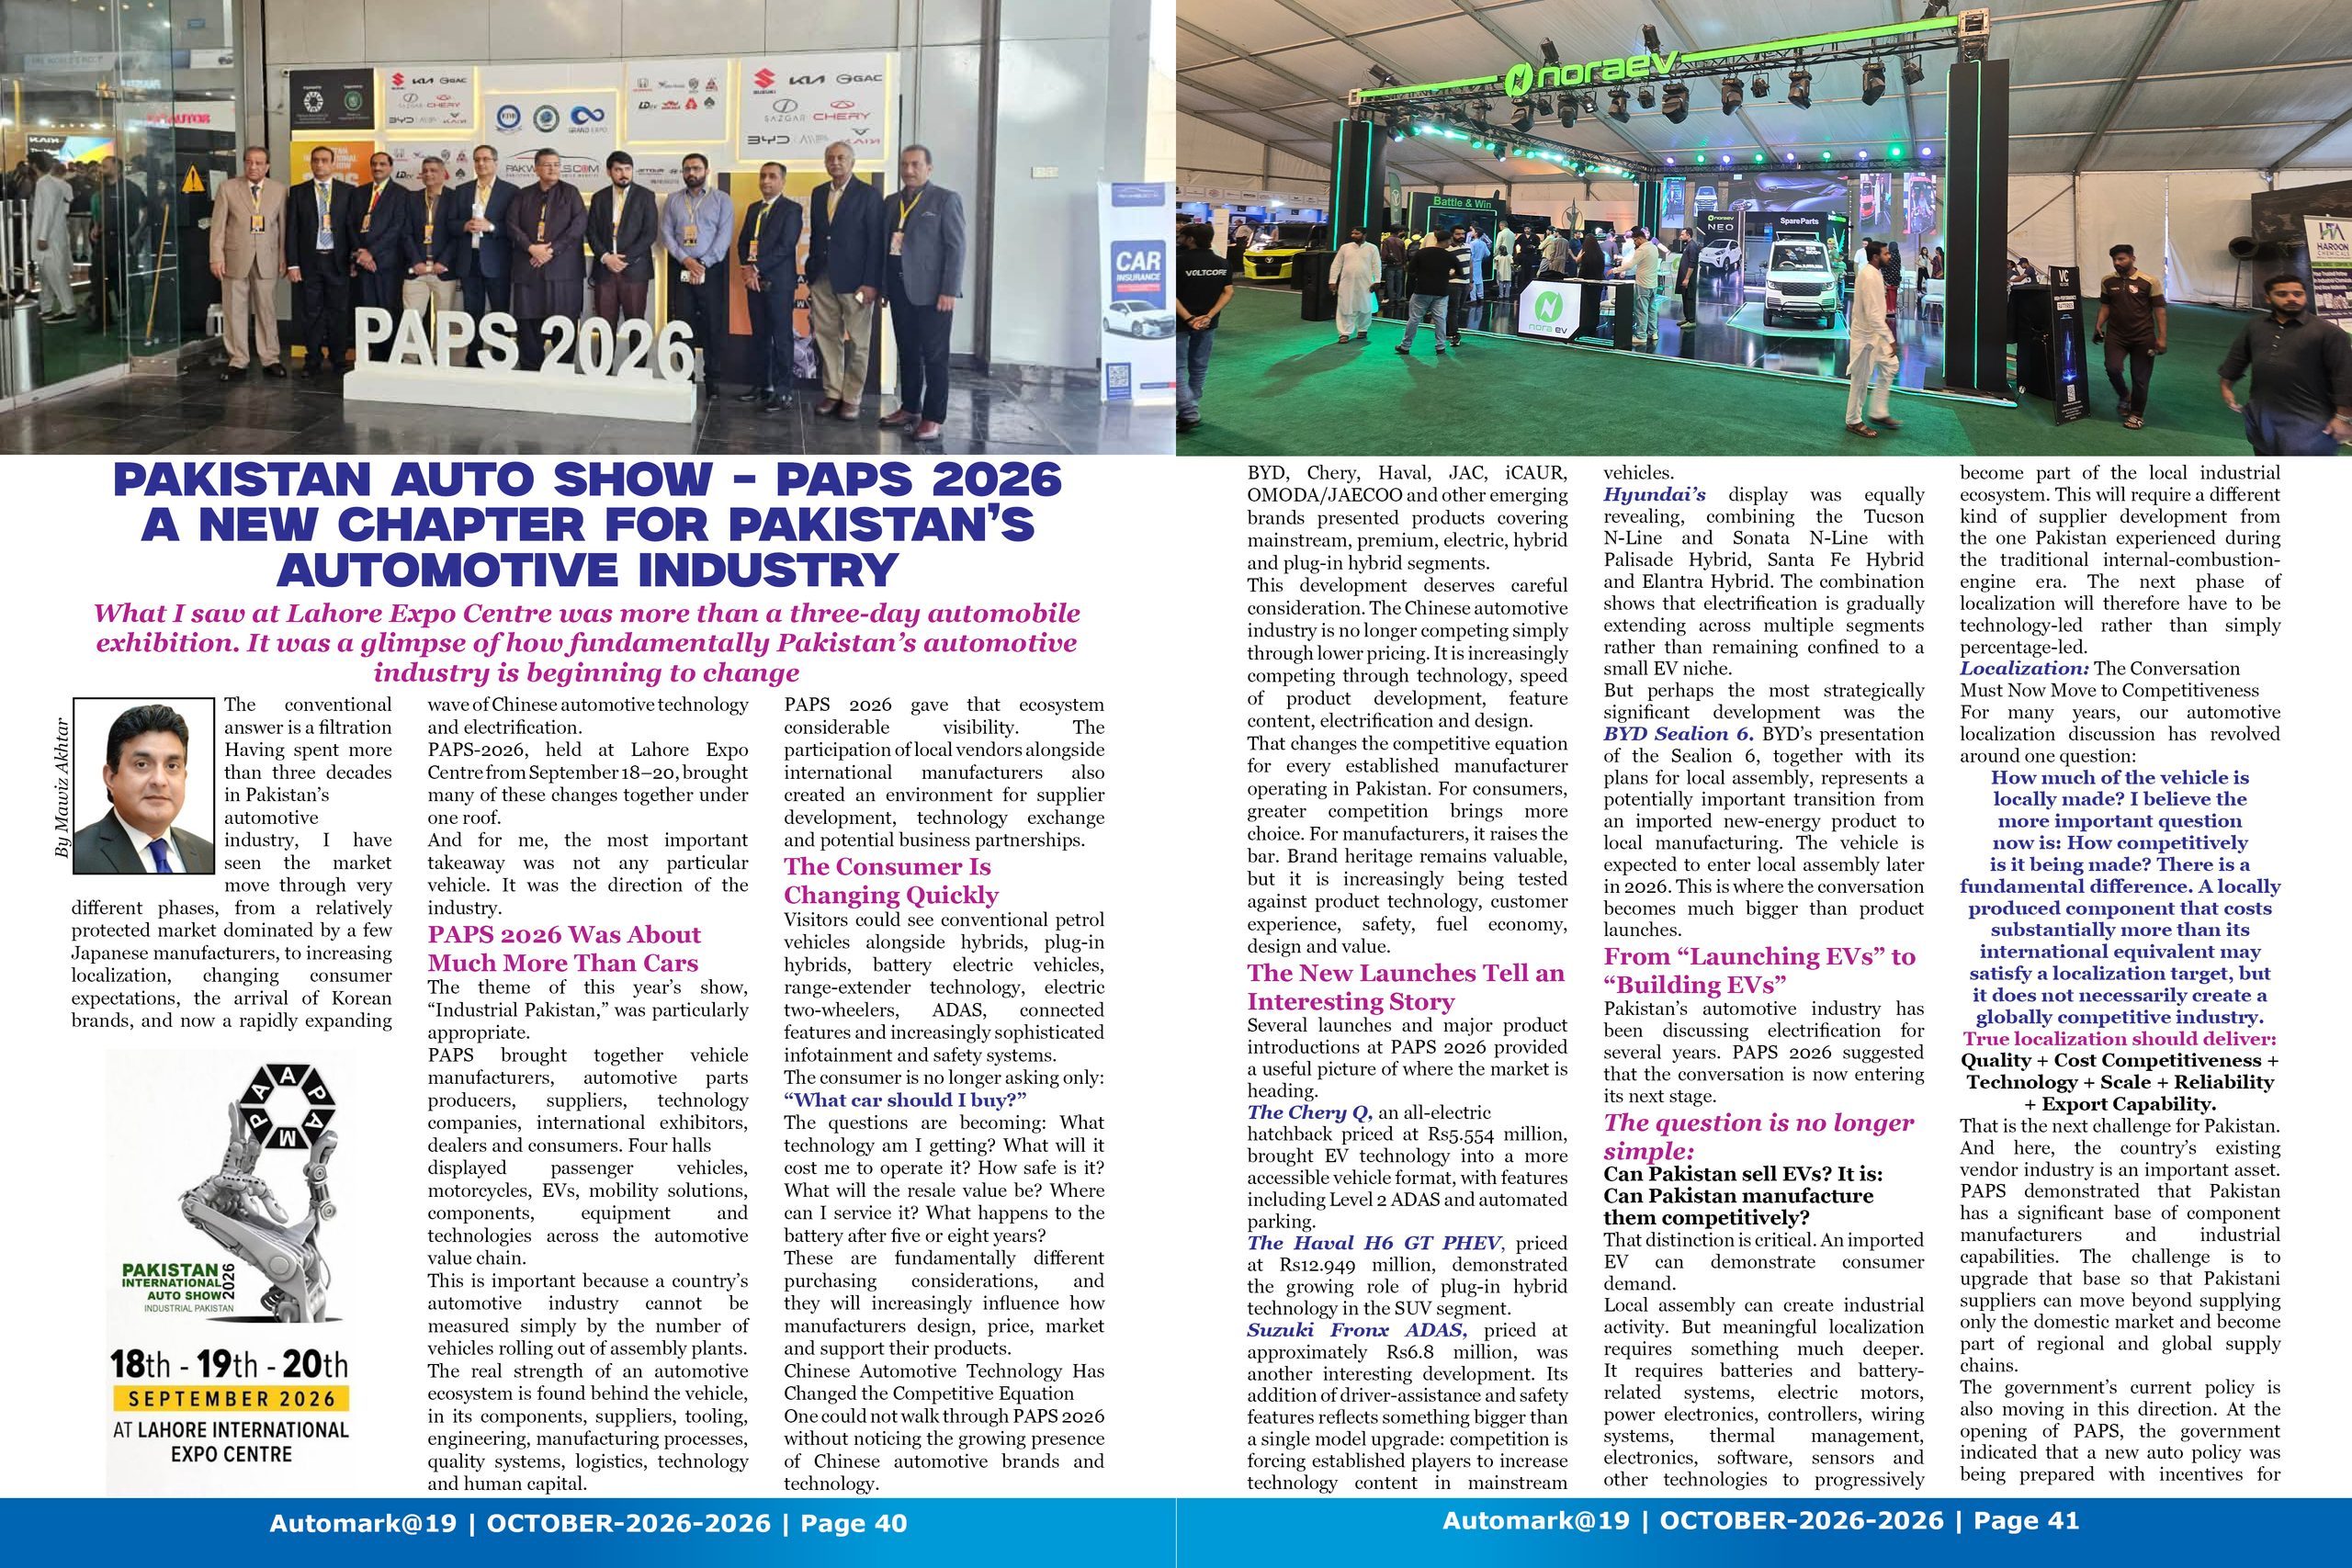
What I saw at Lahore Expo Centre was more than a three-day automobile exhibition. It was aglimpseofhowfundamentallyPakistan’sautomotiveindustryisbeginningtochange.
Having spent more than three decades in Pakistan’s automotive industry, I have seen the market move through very different phases, from a relatively protected market dominated by a few Japanese manufacturers, to increasing localization, changing consumer expectations, the arrival of Korean brands, and now a rapidly expanding wave of Chinese automotive technology and electrification.
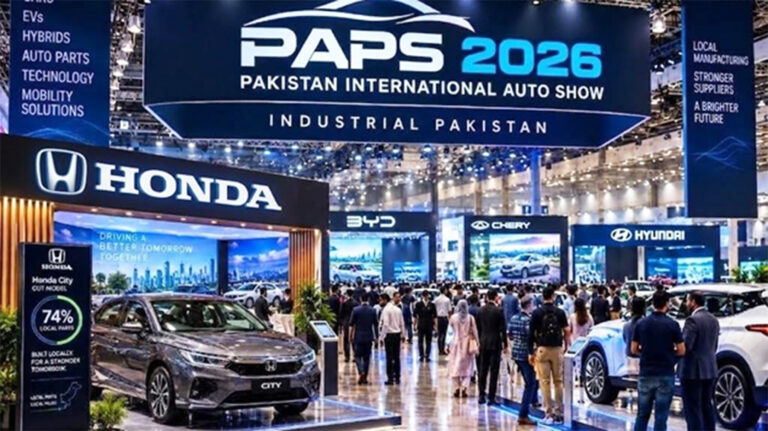
The Pakistan International Auto Show (PAPS) 2026, held at Lahore Expo Centre from September 18–20, brought many of these changes together under one roof.
And for me, the most important takeaway was not any particular vehicle. It was the direction of the industry.
PAPS 2026 Was About Much More Than Cars
The theme of this year’s show, “IndustrialPakistan,” was particularly appropriate.
PAPS brought together vehicle manufacturers, automotive parts producers, suppliers, technology companies, international exhibitors, dealers and consumers. Four halls
displayed passenger vehicles, motorcycles, EVs, mobility solutions, components, equipment and technologies across the automotive value chain.
This is important because a country’s automotive industry cannot be measured simply by the number of vehicles rolling out of assembly plants.
The real strength of an automotive ecosystem is found behind the vehicle, in its components, suppliers, tooling, engineering, manufacturing processes, quality systems, logistics, technology and human capital.
PAPS 2026 gave that ecosystem considerable visibility. The participation of local vendors alongside international manufacturers also created an environment for supplier development, technology exchange and potential business partnerships. The involvement of SMEDA as a strategic partner further underlined the importance of integrating SMEs into the industrial value chain. That, in my view, is one of the most encouraging aspects of this year’s show.
The Consumer Is Changing Quickly
Perhaps the most striking difference from the auto shows of the past was the sheer diversity of technology on display.
Visitors could see conventional petrol vehicles alongside hybrids, plug-in hybrids, battery electric vehicles, range-extender technology, electric two-wheelers, ADAS, connected features and increasingly sophisticated infotainment and safety systems.
The consumer is no longer asking only:
“What car should I buy?”
The questions are becoming: What technology am I getting? What will it cost me to operate it? How safe is it? What will the resale value be? Where can I service it? What happens to the battery after five or eight years?
These are fundamentally different purchasing considerations, and they will increasingly influence how manufacturers design, price, market and support their products.
Chinese Automotive Technology Has Changed the Competitive Equation
One could not walk through PAPS 2026 without noticing the growing presence of Chinese automotive brands and technology.
BYD, Chery, Haval, JAC, iCAUR, OMODA/JAECOO and other emerging brands presented products covering mainstream, premium, electric, hybrid and plug-in hybrid segments.
This development deserves careful consideration. The Chinese automotive industry is no longer competing simply through lower pricing. It is increasingly competing through technology, speed of product development, feature content, electrification and design. That changes the competitive equation for every established manufacturer operating in Pakistan. For consumers, greater competition brings more choice. For manufacturers, it raises the bar. Brand heritage remains valuable, but it is increasingly being tested against product technology, customer experience, safety, fuel economy, design and value.
The New Launches Tell an Interesting Story
Several launches and major product introductions at PAPS 2026 provided a useful picture of where the market is heading.
The Chery Q, an all-electric hatchback priced at Rs5.554 million, brought EV technology into a more accessible vehicle format, with features including Level 2 ADAS and automated parking.
The Haval H6 GT PHEV, priced at Rs12.949 million, demonstrated the growing role of plug-in hybrid technology in the SUV segment.
Suzuki Fronx ADAS, priced at approximately Rs6.8 million, was another interesting development. Its addition of driver-assistance and safety features reflects something bigger than a single model upgrade: competition is forcing established players to increase technology content in mainstream vehicles.
Hyundai’s display was equally revealing, combining the TucsonN-LineandSonataN-Line with PalisadeHybrid,SantaFeHybridandElantraHybrid. The combination shows that electrification is gradually extending across multiple segments rather than remaining confined to a small EV niche.
But perhaps the most strategically significant development was the BYD Sealion 6. BYD’s presentation of the Sealion 6, together with its plans for local assembly, represents a potentially important transition from an imported new-energy product to local manufacturing. The vehicle is expected to enter local assembly later in 2026. This is where the conversation becomes much bigger than product launches.
From “Launching EVs” to “Building EVs”
Pakistan’s automotive industry has been discussing electrification for several years. PAPS 2026 suggested that the conversation is now entering its next stage.
The question is no longer simple:
Can Pakistan sell EVs? It is: Can Pakistan manufacture them competitively?
That distinction is critical. An imported EV can demonstrate consumer demand.
Local assembly can create industrial activity. But meaningful localization requires something much deeper. It requires batteries and battery-related systems, electric motors, power electronics, controllers, wiring systems, thermal management, electronics, software, sensors and other technologies to progressively become part of the local industrial ecosystem. This will require a different kind of supplier development from the one Pakistan experienced during the traditional internal-combustion-engine era. The next phase of localization will therefore have to be technology-led rather than simply percentage-led.
Localization: The Conversation Must Now Move to Competitiveness
For many years, our automotive localization discussion has revolved around one question:
How much of the vehicle is locally made? I believe the more important question now is: How competitively is it being made? There is a fundamental difference. A locally produced component that costs substantially more than its international equivalent may satisfy a localization target, but it does not necessarily create a globally competitive industry. True localization should deliver:
That is the next challenge for Pakistan. And here, the country’s existing vendor industry is an important asset. PAPS demonstrated that Pakistan has a significant base of component manufacturers and industrial capabilities. The challenge is to upgrade that base so that Pakistani suppliers can move beyond supplying only the domestic market and become part of regional and global supply chains.
The government’s current policy is also moving in this direction. At the opening of PAPS, the government indicated that a new auto policy was being prepared with incentives for stakeholders including auto-parts manufacturers, while emphasizing export development.
At the PAAPAM symposium, the discussion centred on competitiveness, localization and electric mobility, with the government emphasizing competitive localization and technological advancement. The direction is encouraging. Execution will determine the outcome.
Perhaps the Most Encouraging Development: Exports
One of the most important developments surrounding PAPS 2026 was not a new vehicle launch at all. It was the growing evidence that Pakistan can move from local assembly towards export-oriented manufacturing.
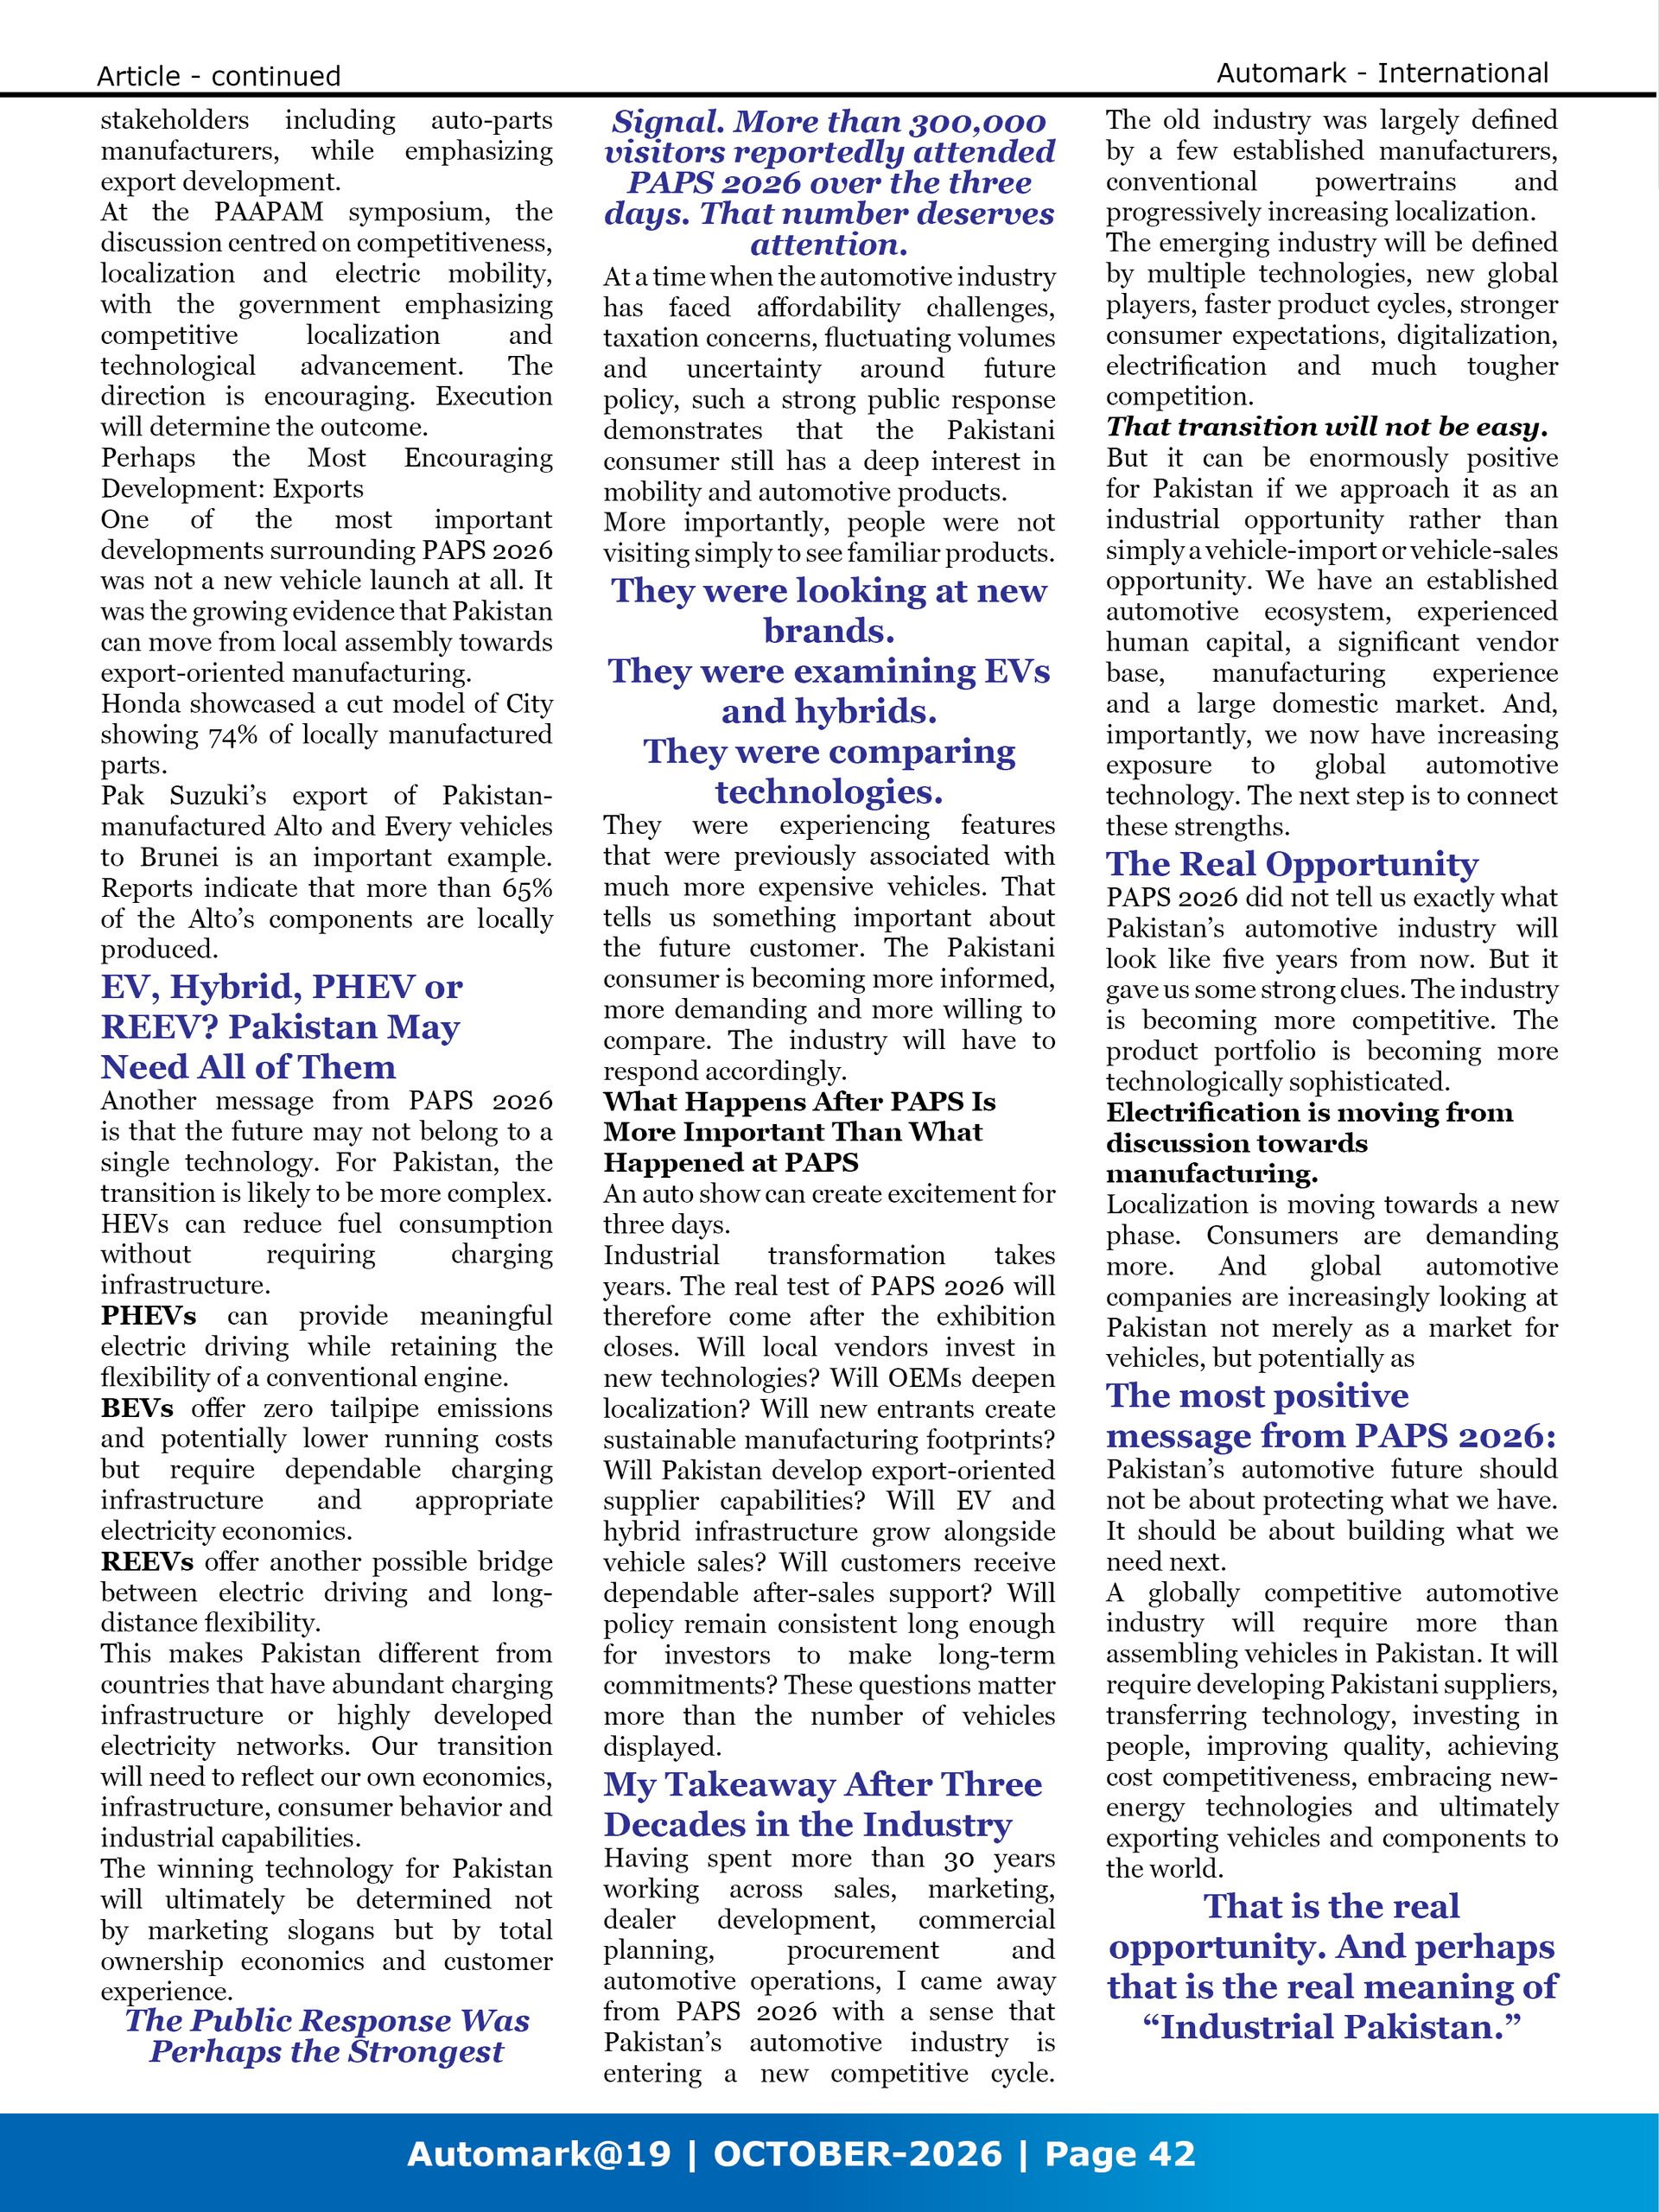
Honda showcased a cut model of City showing 74%oflocallymanufacturedparts.
Pak Suzuki’s export of Pakistan-manufactured Alto and Every vehicles to Brunei is an important example. Reports indicate that more than 65% of the Alto’s components are locally produced.
EV, Hybrid, PHEV or REEV? Pakistan May Need All of Them
Another message from PAPS 2026 is that the future may not belong to a single technology. For Pakistan, the transition is likely to be more complex.
HEVs can reduce fuel consumption without requiring charging infrastructure.
PHEVs can provide meaningful electric driving while retaining the flexibility of a conventional engine.
BEVs offer zero tailpipe emissions and potentially lower running costs but require dependable charging infrastructure and appropriate electricity economics.
REEVs offer another possible bridge between electric driving and long-distance flexibility.
This makes Pakistan different from countries that have abundant charging infrastructure or highly developed electricity networks. Our transition will need to reflect our own economics, infrastructure, consumer behavior and industrial capabilities.
The winning technology for Pakistan will ultimately be determined not by marketing slogans but by total ownership economics and customer experience.
The Public Response Was Perhaps the Strongest Signal. More than 300,000 visitors reportedly attended PAPS 2026 over the three days. That number deserves attention.
At a time when the automotive industry has faced affordability challenges, taxation concerns, fluctuating volumes and uncertainty around future policy, such a strong public response demonstrates that the Pakistani consumer still has a deep interest in mobility and automotive products.
More importantly, people were not visiting simply to see familiar products.
They were looking at new brands. They were examining EVs and hybrids. They were comparing technologies. They were experiencing features that were previously associated with much more expensive vehicles. That tells us something important about the future customer. The Pakistani consumer is becoming more informed, more demanding and more willing to compare. The industry will have to respond accordingly.
What Happens After PAPS Is More Important Than What Happened at PAPS
An auto show can create excitement for three days.
Industrial transformation takes years. The real test of PAPS 2026 will therefore come after the exhibition closes. Will local vendors invest in new technologies? Will OEMs deepen localization? Will new entrants create sustainable manufacturing footprints? Will Pakistan develop export-oriented supplier capabilities? Will EV and hybrid infrastructure grow alongside vehicle sales? Will customers receive dependable after-sales support? Will policy remain consistent long enough for investors to make long-term commitments? These questions matter more than the number of vehicles displayed.
My Takeaway After Three Decades in the Industry
Having spent more than 30 years working across sales, marketing, dealer development, commercial planning, procurement and automotive operations, I came away from PAPS 2026 with a sense that Pakistan’s automotive industry is entering a newcompetitive cycle. The old industry was largely defined by a few established manufacturers, conventional powertrains and progressively increasing localization. The emerging industry will be defined by multiple technologies, new global players, faster product cycles, stronger consumer expectations, digitalization, electrification and much tougher competition.
That transition will not be easy. But it can be enormously positive for Pakistan if we approach it as an industrial opportunity rather than simply a vehicle-import or vehicle-sales opportunity. We have an established automotive ecosystem, experienced human capital, a significant vendor base, manufacturing experience and a large domestic market. And, importantly, we now have increasing exposure to global automotive technology. The next step is to connect these strengths.
The Real Opportunity
PAPS 2026 did not tell us exactly what Pakistan’s automotive industry will look like five years from now. But it gave us some strong clues. The industry is becoming more competitive. The product portfolio is becoming more technologically sophisticated. Electrification is moving from discussion towards manufacturing. Localization is moving towards a new phase. Consumers are demanding more. And global automotive companies are increasingly looking at Pakistan not merely as a market for vehicles, but potentially as
The most positive message from PAPS 2026: Pakistan’sautomotivefutureshouldnotbe aboutprotectingwhatwehave.Itshouldbeaboutbuildingwhatweneednext.
A globally competitive automotive industry will require more than assembling vehicles in Pakistan. It will require developing Pakistani suppliers, transferring technology, investing in people, improving quality, achieving cost competitiveness, embracing new-energy technologies and ultimately exporting vehicles and components to the world.
That is the real opportunity. And perhaps that is the real meaning of “IndustrialPakistan.”
The growth of Chinese automotive brands in Pakistan has been significant, driven by competitive pricing, modern design, advanced technology and an increasingly attractive product portfolio.
However, the next challenge for Chinese automotive brands is no longer simply selling more vehicles. The real opportunity is to build long-term customer trust, loyalty and confidence throughout the entire ownership journey.
At the center of this challenge is After-Sales Service.
After-Sales: The Foundation of Long-Term Customer Confidence
As the population of Chinese vehicles on Pakistani roads continues to grow, customers will increasingly judge brands not only by the vehicle they purchase, but by the quality and reliability of the support they receive after the sale.
Spare-parts availability, competitive pricing, service quality, technical support and response time will become critical differentiators.
Manufacturers and dealers therefore need to establish robust after-sales capabilities focused on:
– High spare-parts availability and supply fill rates – Competitive spare-parts pricing and an attractive total cost of ownership – Short, predictable and reliable shipping lead times – Accurate demand forecasting – Efficient ordering and replenishment processes – Strong technical support and service capabilities – Effective customer communication and issue resolution
After-sales performance must become an integral part of the brand proposition rather than being treated simply as a dealer operational responsibility.
Spare Parts Availability: A Joint Responsibility
Parts availability is not merely a matter of maintaining sufficient inventory at dealerships.
It is the result of an integrated ecosystem involving the vehicle manufacturer, local distributor, dealer network, logistics providers, information systems and operational processes.
A breakdown in any one of these areas can ultimately affect the customer.
For example, a part may be physically available at the manufacturer but unavailable to the customer because of delays in ordering, documentation, logistics, customs clearance, system integration or dealer processes.
This makes supply-chain integration critical to delivering a consistent customer experience.
Building a Professional After-Sales Infrastructure
To support sustainable growth in Pakistan, Chinese automotive manufacturers should establish professional and scalable after-sales infrastructure covering the complete parts and service value chain.
Key capabilities should include:
1. Accurate Electronic Parts Catalogues Professional electronic parts catalogues should provide accurate part numbers, VIN/application information and clear identification of applicable vehicle variants.
2. Efficient Dealer Parts Ordering Systems Dealers should have simple, reliable and transparent systems for placing, tracking and managing parts orders.
3. Clear and Reliable Shipping Lead Times Dealers and customers should have realistic delivery expectations supported by reliable logistics processes.
4. Strong Supply Fill Rates and Order Fulfilment The objective should be to maximize first-time fulfilment and minimize customer waiting time.
5. Effective Urgent and Back-Order Processes Clearly defined procedures should exist for critical, urgent and back-ordered parts, with appropriate escalation mechanisms.
6. Manufacturer–Dealer System Integration Integration between the manufacturer’s systems and the dealer’s Dealer Management System (DMS) can improve visibility, forecasting, ordering, inventory management and customer communication.
The Customer Sees Only One Brand
From the customer’s perspective, responsibility is straightforward.
If a required part is unavailable or a repair is delayed, the customer generally does not distinguish whether the problem originated with the dealer, manufacturer, logistics provider, ordering system or supply chain.
The customer simply experiences it as a brand problem.
This is why after-sales performance should be managed as a joint manufacturer–dealer responsibility, supported by clearly defined processes, ownership and measurable performance indicators.
Important KPIs should include:
– Parts availability – Supply fill rate – Order accuracy – Order fulfilment – Delivery lead time – Back-order ageing – Emergency parts response time – Customer repair turnaround time – Warranty claim turnaround time – Customer satisfaction
What gets measured, reviewed and improved consistently is far more likely to become a sustainable competitive capability.
The Benchmark Already Exists in Pakistan
Pakistani customers have experienced established after-sales standards from Japanese and Korean automotive brands. As a result, customer expectations have been shaped not only by vehicle quality, but also by parts availability, service quality, technical expertise, pricing, reliability and customer care.
Chinese automotive brands therefore enter the Pakistani market with an important opportunity—and a clear benchmark.
They have already demonstrated their ability to compete strongly in areas such as vehicle design, technology, features and pricing.
The next step is to demonstrate the same level of excellence in after-sales operations, spare-parts availability and supply-chain reliability.
From Selling Vehicles to Managing the Ownership Journey
The automotive business is not completed when a vehicle is delivered to the customer.
In many respects, that is where the customer relationship truly begins.
Every service visit, spare-parts requirement, warranty claim and technical interaction becomes another opportunity for the brand to either strengthen or weaken customer confidence.
Chinese automotive brands that develop a strong after-sales ecosystem from the beginning can convert vehicle sales into long-term customer relationships.
This requires close alignment between the manufacturer and dealer network, investment in systems and processes, strong parts planning, professional technical support and a customer-centric service culture.
The Strategic Imperative
The future success of Chinese automotive brands in Pakistan will depend not only on how many vehicles they sell, but on how effectively they support those vehicles throughout their ownership lifecycle.
Selling the car is only the beginning. Supporting the customer throughout the ownership journey is what builds the brand.
The next competitive advantage in Pakistan’s automotive industry may therefore not be found only in the showroom.
It may be found in the parts warehouse, the supply chain, the workshop, the technical support center and every customer interaction after the sale.